This is the old-school pension from your grandpa’s factory job—a monthly check for life. If you die before retiring, this one plays hard to get. Usually, your spouse gets a smaller version of that monthly check, like a “survivor’s benefit” that’s about half or two-thirds of what you would have received.
But here’s the kicker: if you die after you’ve already retired, the rules can change. If you took the “single life” payout (more money for you each month), the checks stop cold when you die. Sorry, kids. It’s like ordering the large pizza, eating all the slices yourself, and leaving the box empty.
However, if you chose the “joint life” option with your spouse (a slightly smaller check each month), the payments keep going to them for the rest of their life. It’s the financial equivalent of saying, “I had a slice, but I saved you a whole half.” It’s a romantic gesture, buried in actuarial tables.
What About the “Personal Slice” Pension? (Defined Contribution)
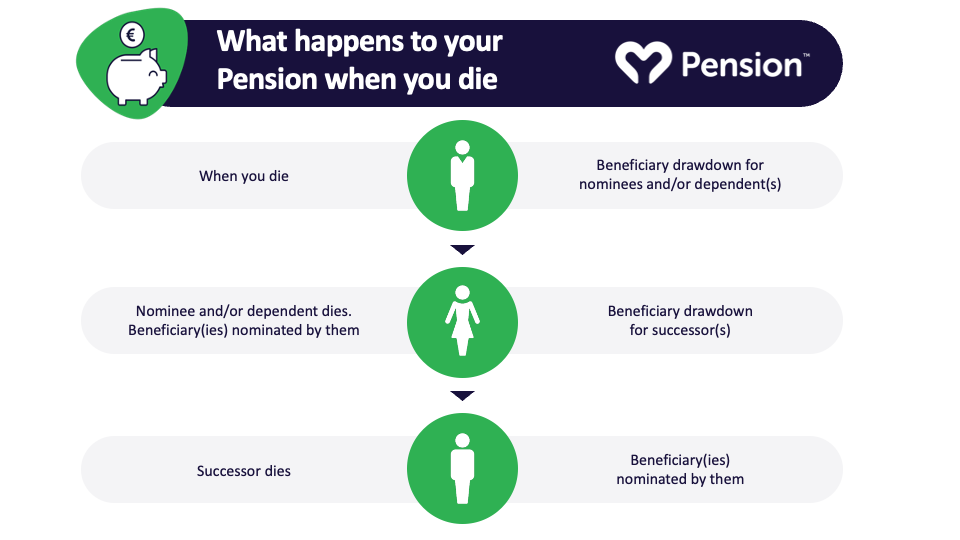
This is the 401(k) or IRA—your own little retirement piggy bank. This is where things get much simpler and, frankly, more generous. That entire pot of money? It belongs to your estate or to a named beneficiary.
 What Happens to Your Pension When You Die? The UK Rules Most People Don
If you named your spouse, they can usually roll it into their own retirement account without a tax hit. They can treat it like it’s their own pizza now. If you named your daughter, your friend, or even your cat (if you’re weird enough), they get the entire leftover slice.
The tricky part is the inheritance tax. Depending on your country, your beneficiaries might have to pay a slice of that pizza back to the taxman. It’s like ordering delivery and realizing you have to tip the driver before you can eat.

